

Payday Cash Advance TriceLoans
4.7

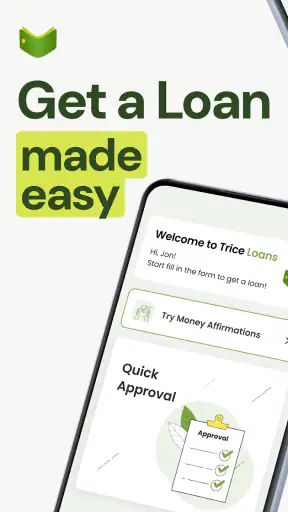
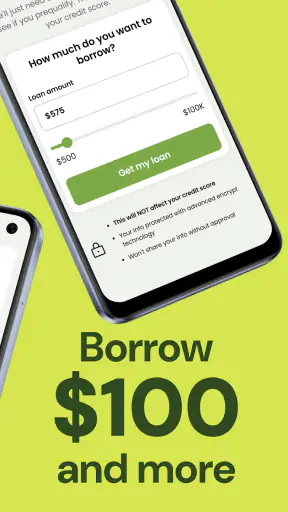
When money is tight at home, a cash-advance app can look like a simple way to cover a short gap. I approached Payday Cash Advance TriceLoans with that practical question in mind: could it fit into a shared household without creating confusion about who is borrowing, what is being agreed to, or how repayment will affect the next pay cycle? My experience is that it is best treated as a personal borrowing tool, not as a household wallet or a shared financial dashboard.
The app sits in the finance category and is developed by Trice Loans. It is free to install, carries an Everyone age rating, and presents itself as a way to request a payday cash advance through a mobile loan process. Its store summary emphasizes speed and no credit check, which explains the app’s appeal when an unexpected bill arrives. At the same time, those conveniences should not be mistaken for free money. A cash advance is still a financial commitment, and the right decision depends on whether the next income payment can comfortably absorb it.
I found the most useful way to judge it is to separate access from responsibility. One person may install the app, but a partner, parent, or roommate could still be affected by the resulting repayment pressure. That distinction matters more than the bright promise of fast access. The app may help with timing, but it cannot solve an income shortfall that continues from one pay period to the next.
How TriceLoans fits into a shared household
A realistic emergency scenario
Imagine a household where one person handles groceries and another normally covers transport. A utility payment arrives earlier than expected, while the next paycheck is still several days away. The person whose name is on the borrowing request may open TriceLoans because the need feels urgent. That can be reasonable if the amount is genuinely temporary and the repayment plan is understood before accepting anything.
The difficult part begins when the app is treated as if it belongs to everyone. If a partner assumes the advance is shared money, or if a roommate uses the same phone without realizing an application is open, the household can quickly lose track of the decision. I would keep the borrowing conversation outside the app as well: explain why the money is needed, who will repay it, and which regular expense may need to be reduced afterward.
This is one area where the app’s simplicity can work both ways. A focused loan interface may reduce distractions when someone is dealing with an urgent expense, but a short process can also encourage a rushed decision. Before proceeding, I would write down the amount needed, the date income is expected, and the maximum repayment that can be handled without borrowing again.
Why a shared device needs clear boundaries
Households often share tablets or phones, especially when a family member needs help with an online task. That does not make a finance app a shared account. I recommend that the person considering an advance use only their own device profile or a private session and avoid leaving an application screen open for someone else to continue accidentally.
I would also avoid handing the phone to a partner or child with the app already positioned at a decision screen. Even when the intention is simply to ask for help reading a form, the financial choice should remain with the person whose name and income are involved. A second person can review the information verbally, but the applicant should personally check every important field before submitting anything.
There is a practical household benefit to this separation: it creates a clean record of responsibility. If two adults need separate advances, each should evaluate the situation independently rather than assuming one request automatically covers both needs. Combining separate financial problems into one rushed application can make the repayment burden harder to understand.
What I would prepare before opening the app
My preferred workflow is deliberately unexciting. I first check the bank balance, list the bills due before the next income payment, and identify the smallest amount that would solve the immediate problem. Then I consider whether postponing a purchase, asking a bill provider for more time, or using an existing emergency fund would be less expensive than borrowing.
Only after that would I open TriceLoans. I would keep identification and income details nearby, use a stable internet connection, and read the complete offer rather than focusing only on the amount displayed. The store information describes the service as a payday cash advance and highlights no credit check, but that does not remove the need to understand the actual repayment obligation presented during the process.
A useful tip is to take personal notes about the offer before accepting it: amount received, total amount owed, expected repayment date, and any optional charge shown on screen. This is not a substitute for reading the app’s terms; it simply makes the commitment easier to discuss with someone else in the household and easier to compare with alternatives.
Setup, coordination, and financial trust
Keep the account boundary personal
TriceLoans should be approached as an individual finance app. I would not share login details, verification codes, or access to a device that is still signed in. A spouse or trusted relative may help someone understand a screen, but sharing credentials creates confusion about who authorized an action and who is responsible for the resulting obligation.
This matters particularly when a household uses one phone number for practical reasons or when an older family member asks a younger relative to complete the application. Assistance is fine; substitution is risky. The person taking the advance should be present, understand the terms, and make the final decision themselves.
I also recommend closing the app after use and reviewing the device’s normal security settings. I am not suggesting that TriceLoans provides special household controls; rather, basic device privacy is the sensible way to prevent accidental access to a sensitive finance session. A shared screen is not the same thing as shared consent.
Coordinate before, not after, borrowing
In my view, the best household use case is coordinated emergency planning. Two adults can agree that one person will investigate the advance while the other checks the budget. That division keeps the process efficient without pretending that the app is designed for joint financial management.
For example, one person could calculate which bill is most urgent while the applicant checks the available loan information. Once the details are visible, both can discuss whether the repayment date clashes with rent, groceries, transport, or other fixed commitments. The applicant should then make the final choice, but the conversation can expose a problem that is easy to miss when someone is focused only on getting cash quickly.
Another useful habit is to record the repayment date in the household calendar without storing sensitive account details there. A neutral reminder such as “review advance repayment” can prompt a budget check before the due date. This helps prevent the common mistake of treating the advance as extra income instead of money pulled forward from a future pay period.
When another option is better
TriceLoans makes more sense for a narrow, short-lived timing problem than for recurring expenses. If the same household is short every month, a payday advance may only move the pressure forward. In that situation, I would look first at a written budget, a payment arrangement with the bill provider, a credit-union alternative, or a trusted emergency fund. Those routes may take more effort, but they can be better suited to an ongoing gap.
A conventional bank or credit-union product may also be preferable when a borrower has time to compare annual costs and repayment schedules. A credit card can be less expensive in some circumstances, though it carries its own risks and should not be used casually. The right comparison is not “which app is fastest?” but “which option leaves the household in the strongest position after the emergency has passed?”
The app’s no-credit-check positioning may attract people who expect difficulty with traditional borrowing. That can be useful in a limited situation, but it should not encourage someone to skip affordability checks. A quick approval path, if available for a particular applicant, does not make repayment optional or remove the consequences of taking on too much.
Age context and trust
The Everyone rating describes the app’s general content suitability, not whether every person is financially ready to borrow. I would not interpret that rating as an invitation for children or teenagers to manage loan decisions. In a family setting, adults should keep borrowing activity separate from a child’s device use and explain in plain language that an advance creates a future obligation.
This is especially important when a young person helps an older relative with technology. The helper can read instructions, enlarge text, or explain where information belongs, but should not pressure the applicant to accept an offer. The safest arrangement is for the borrower to remain beside the device, review each detail, and confirm the decision personally.
Trust also needs a practical limit. Even between partners, I would avoid assuming that shared finances mean automatic permission to use one another’s account. Discussing the request openly is healthy; silently submitting it under someone else’s details is not. That boundary protects both people if the household later needs to understand what happened.
Costs, optional purchases, and careful reading
The app itself is free to install, while its listing also shows in-app purchases ranging from $1.99 to $4.99 per item. I would not treat the installation price as the full cost of using a borrowing service. The important figures are the terms shown for the specific advance, including what must be repaid and when. Any optional purchase should be understood before it is selected, especially on a device where another person may have access.
This is another reason I prefer a two-person review without shared credentials. The applicant can read the offer aloud, while a partner checks the household budget. If something is unclear, pause rather than guessing. Financial screens deserve slower attention than ordinary shopping screens because a small misunderstanding can affect the next pay cycle.
The current version is 1.1.6, and the app supports Android 7.0 or later. That makes compatibility relevant for households using an older Android phone. I would update the phone through its normal system process when appropriate and avoid relying on a device that is unstable, nearly full, or regularly used by several people during a time-sensitive application.
What the rating and adoption suggest
TriceLoans holds a 4.7 average from around 7,200 ratings, with more than 50,000 installs. Those figures suggest that many people have found the app worth trying, and they help establish that it is not an obscure download with no user activity. Still, a strong average rating cannot tell me whether a particular advance is affordable for my household.
Finance-app reviews often reflect ease of use or speed, while the most important personal question is what happens after the money arrives. I would use the rating as a sign to inspect the app, not as a reason to borrow. The developer, Trice Loans, provides the product, but the household still needs its own decision process and repayment plan.
My household verdict after weighing the trade-offs
I see Payday Cash Advance TriceLoans as a focused option for an adult who faces a genuine short-term cash gap and is willing to examine the repayment commitment carefully. Its free installation, finance-focused design, and emphasis on quick access make it easy to understand why someone might consider it during an urgent week. The no-credit-check message may also appeal to borrowers who do not expect traditional lenders to be helpful.
However, I would not place it in the center of a shared household’s financial system. It is not a substitute for joint budgeting, a family emergency fund, or a transparent conversation about recurring shortfalls. On a shared device, I would keep the session private, make sure the applicant is the person making the decision, and discuss the consequences before any acceptance step.
My strongest practical recommendation is to borrow only the minimum that solves the immediate problem and to compare the repayment date with every essential household expense. If the advance would require another advance, it is probably addressing the symptom rather than the cause. If a bill can be delayed or covered through a less costly option, that route deserves priority.
For a one-off emergency, the app may be worth examining. For regular household budgeting, I would choose a tool designed for expense tracking or a financial arrangement that makes long-term costs clearer. That distinction is the key to using Payday Cash Advance TriceLoans responsibly: keep the account personal, coordinate openly, protect younger or less experienced household members from making the decision, and never confuse fast access with an affordable solution.
4.7
199.00 Reviews
Pros
- Quick online application with a simple
- user-friendly process.
- May help cover urgent expenses before your next paycheck.
- Available information can make loan terms easier to compare.
- Convenient access from a mobile device at any time.
- Useful for borrowers who may not qualify for traditional bank loans.
Cons
- Short repayment periods can make monthly payments difficult to manage.
- Interest and fees may be high compared with conventional loans.
- Approval
- rates
- and loan amounts depend on lender eligibility checks.
- Not available in every state or to all applicants.
- Late payments may lead to extra fees or damage your credit profile.


